November 6, 2026|2 min read
Kenya Proposes Open Banking Rules to Reshape Its Fintech Industry
Kenya's proposed open banking framework could increase competition in digital finance while giving fintech companies new opportunities to access financial data securely.
BY THEGREYIT
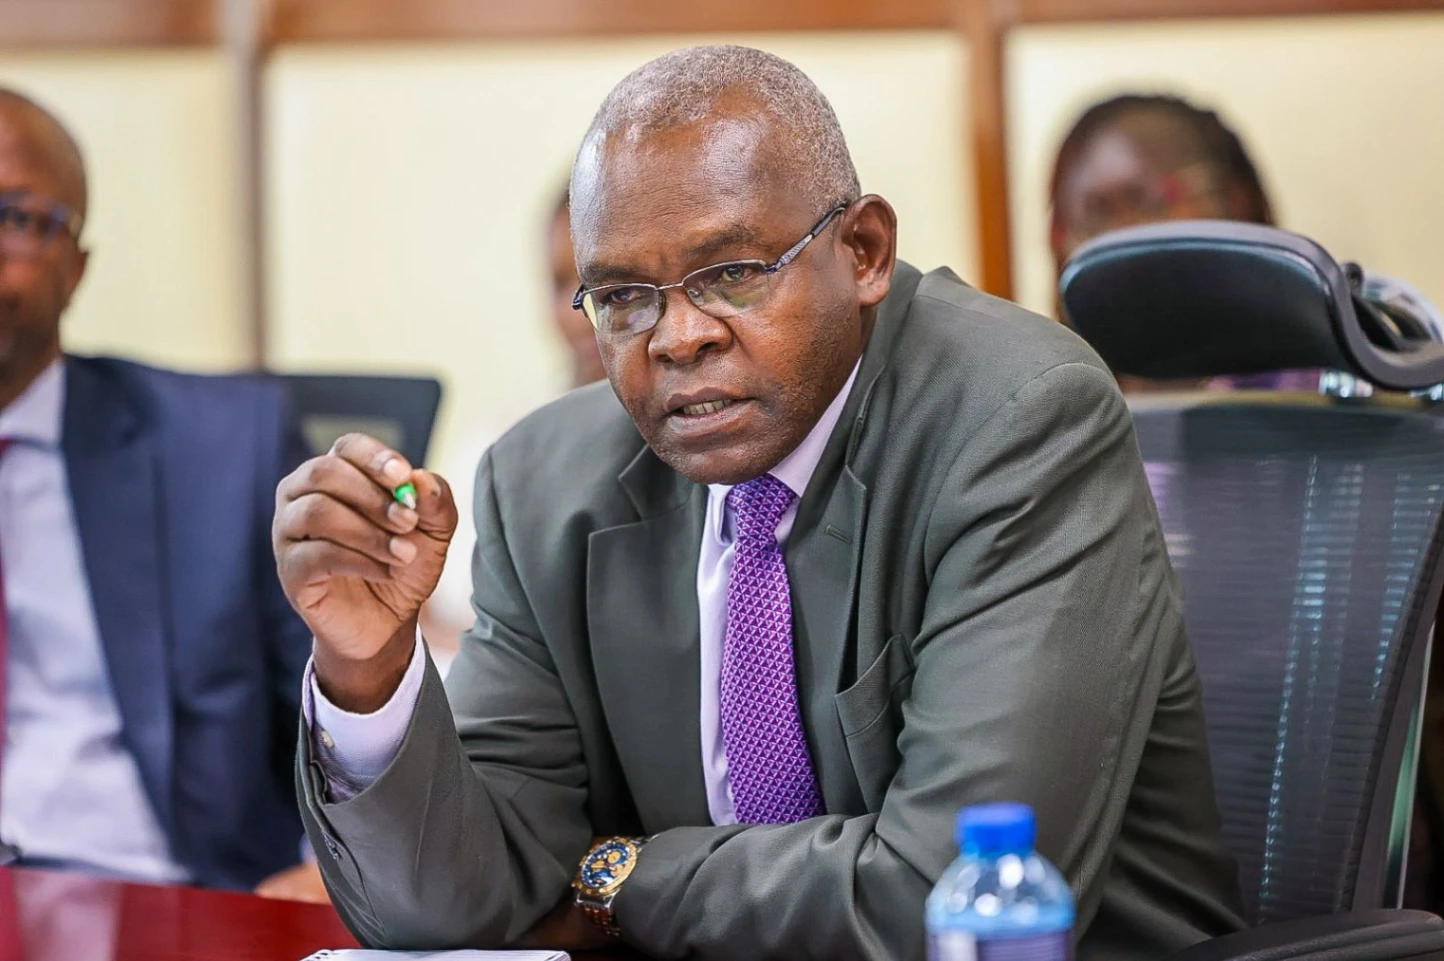
Kenya is taking steps towards transforming its digital financial services industry after the Central Bank of Kenya (CBK) proposed new regulations that could change how banks, mobile money operators and fintech companies share financial information.
The proposed reforms are contained in the National Payment System Bill, 2026, which seeks to replace existing legislation governing electronic payment services. Published for public consultation on September 21, 2026, the bill introduces an open banking framework that would allow authorised fintech providers to access customer financial information with proper consent.
Under the proposed framework, financial institutions and payment operators would be required to adopt interoperable technologies, including open application programming interfaces (APIs). This could make it easier for fintech companies to develop financial products without depending entirely on infrastructure controlled by traditional banks.
Two new categories of providers would also be introduced: Payment Initiation Service Providers and Account Information Service Providers. While the former would facilitate payments on behalf of customers, the latter would allow users to view financial information from multiple accounts through a single platform. Neither category would be permitted to hold customer funds directly.
However, the reforms would introduce stricter licensing and financial requirements. Minimum capital thresholds would range from KSh 5 million for certain specialised providers to KSh 250 million for electronic money issuers.
The CBK would also receive broader supervisory powers, including the authority to inspect payment operators, restrict activities and intervene when businesses face serious regulatory difficulties.
For fintech startups, these changes could create opportunities in digital payments, financial management and alternative credit assessment. However, stronger cybersecurity requirements, data protection obligations and compliance costs could create additional challenges, particularly for smaller companies.
At TheGreyIT, we believe open banking could become an important driver of financial innovation across Africa. However, successful implementation will depend on balancing access to financial data with customer privacy, cybersecurity and fair competition.
With the public consultation period closed on October 9, 2026, the proposed legislation still requires further legislative approval before becoming law.
Recent Blogs
Africa Must Build Its Own Data Centres to Secure Its AI Future
By THEGREYIT
November 10, 2026
Nclude Secures $112 Million to Fund African Fintech and AI Startups
By THEGREYIT
November 9, 2026
Kenya Proposes Open Banking Rules to Reshape Its Fintech Industry
By THEGREYIT
November 6, 2026
Egypt’s Nclude Secures $112 Million to Expand Fintech and AI Investments Across Africa
By THEGREYIT
November 5, 2026